Documentation · Adjusters · Deductibles
Roof Insurance Claims in Myrtle Beach, SC
Most people learn how their storm coverage works during the worst week of the year. Here's the version you can read beforehand.
Where We Stand
What a Roofer Should and Shouldn't Do on Your Claim
There's a line here, and companies that cross it are usually the ones you should worry about.
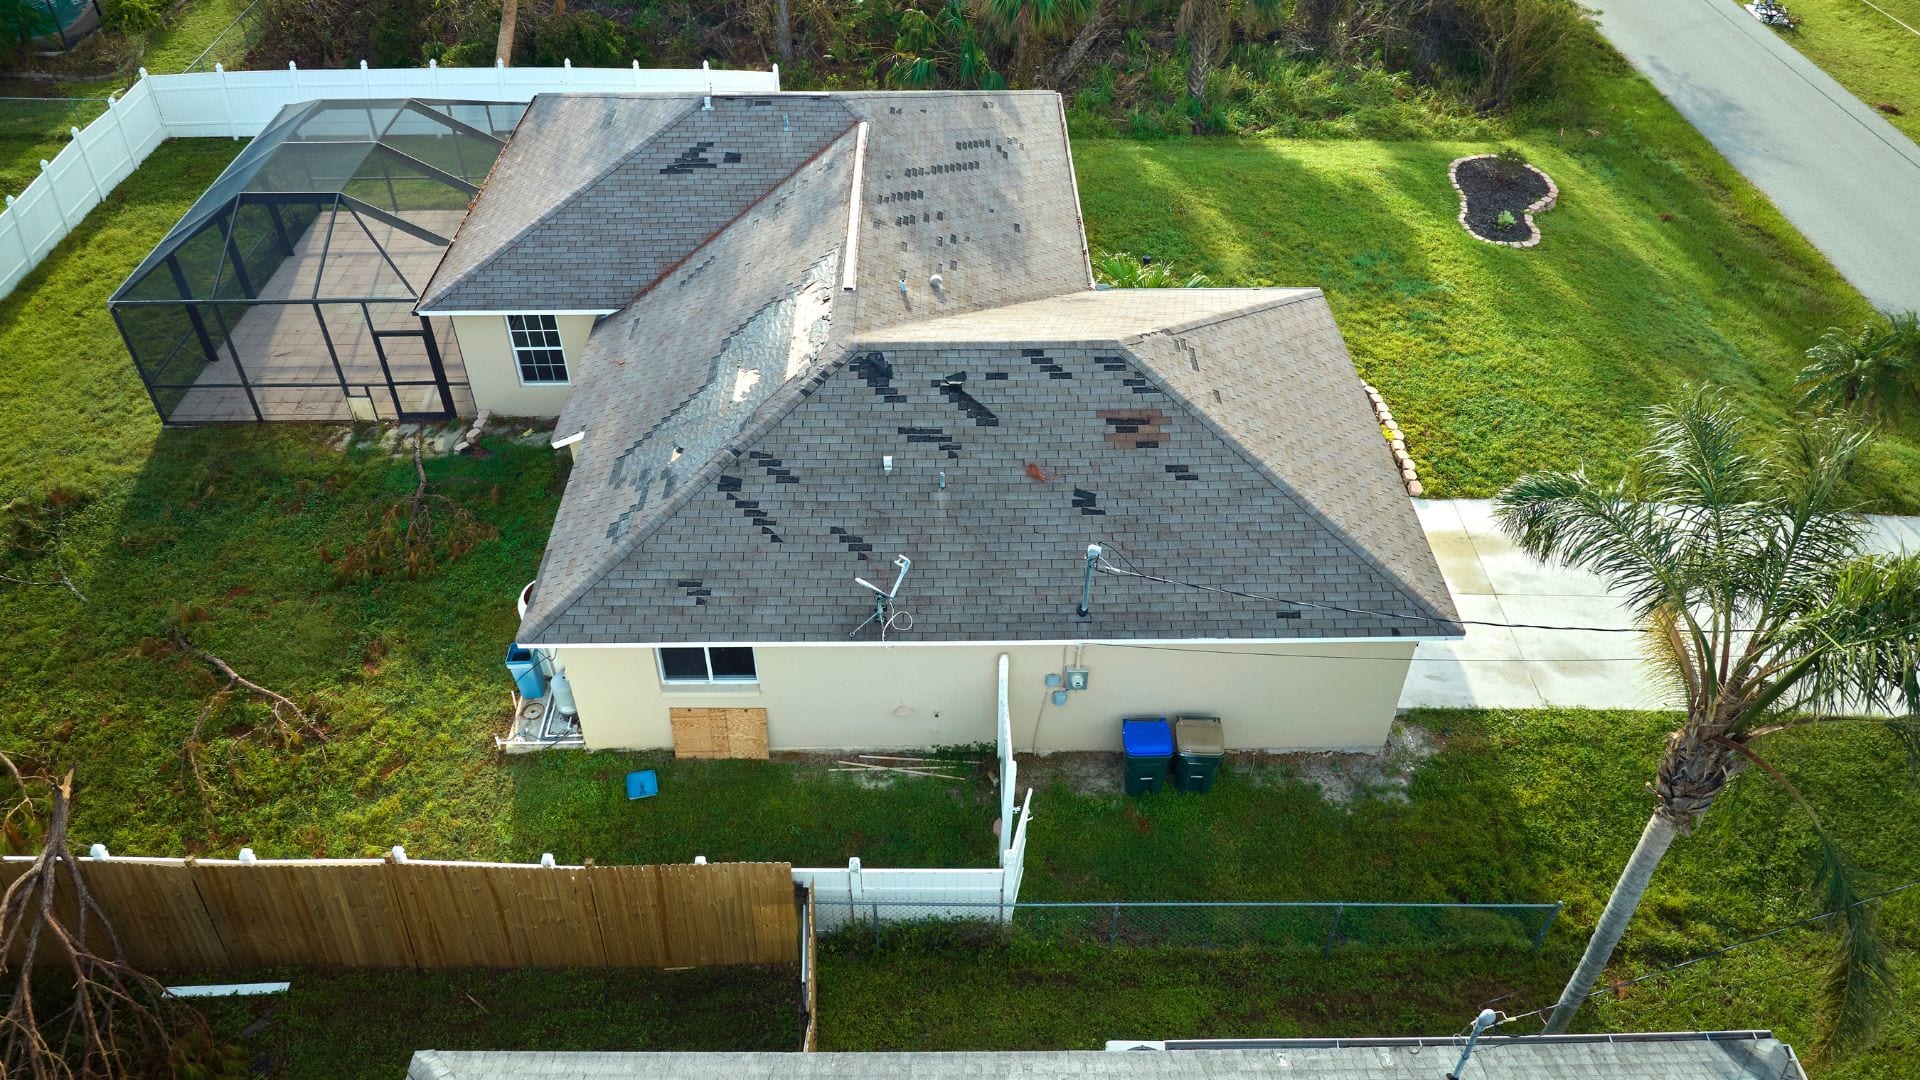
Our job on a claim is straightforward: get on the roof, find what's actually damaged, photograph it properly with the storm date attached, and be standing there when your adjuster comes out so everyone is looking at the same thing. That documentation is genuinely useful, and it costs you nothing.
What we don't do is negotiate your claim. Adjusting a claim on a homeowner's behalf is regulated work in South Carolina and it isn't a roofing contractor's role. Any company promising to handle your insurance company for you, or offering to make your deductible disappear, has told you something important about how they operate.
Costly Mistakes
Where Coastal Claims Go Sideways
Five things that cost Grand Strand homeowners real money on otherwise valid claims.
-
Not Knowing the Wind Deductible
A percentage-based named-storm deductible can be many times the standard one.
-
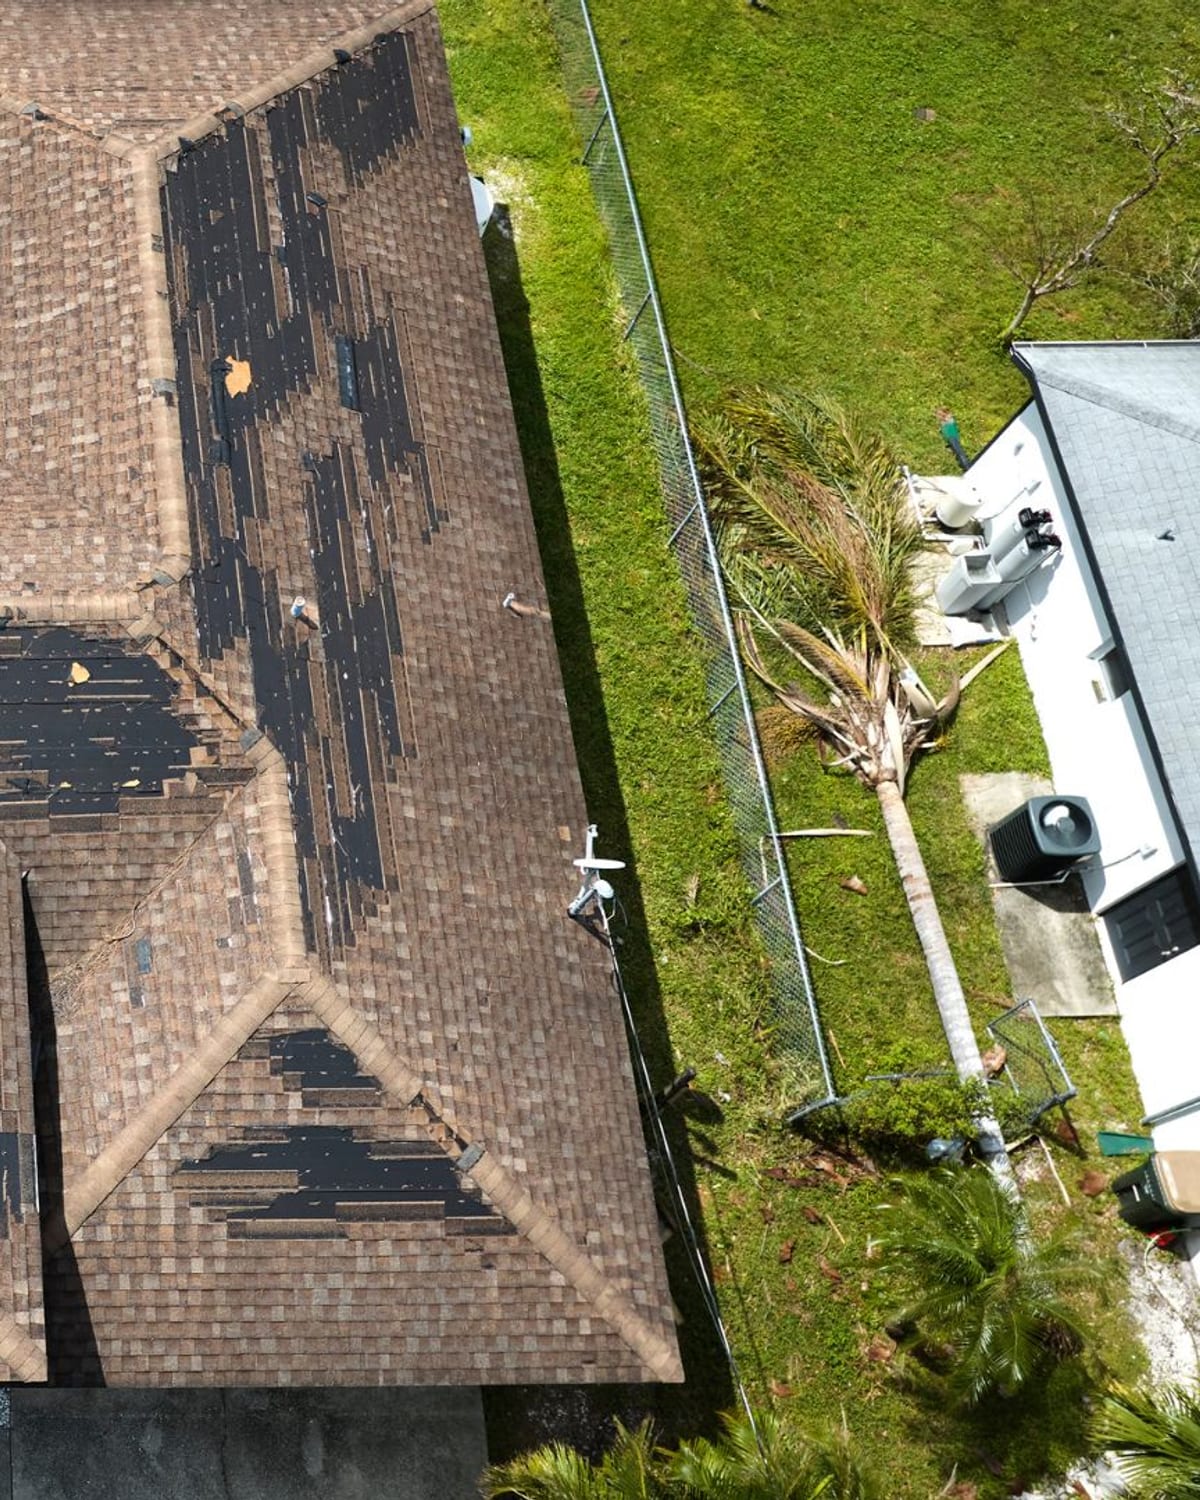
Cleaning Up Before Documenting
Clearing debris and shingle pieces removes the evidence the adjuster needs to see.
-
Waiting Past the Reporting Window
Policies set deadlines for storm loss, and some carriers enforce them strictly.
-
Signing With a Door Knocker
Post-storm contracts signed on the porch often contain assignment clauses people regret.
-
Filing on Damage Below the Deductible
A claim that pays nothing can still affect your record and future premium.
Claim Sequence
How a Storm Claim Runs From Start to Finish
Four steps, in the order that keeps your options open.
-
Get It Documented First
Free inspection with photos tied to the storm date, before anything is touched.
-
Compare Against the Deductible
Know the repair cost and your actual deductible before deciding to file.
-
File and Meet the Adjuster
You file; we're on the roof with the adjuster so nothing gets missed.
-
Approved Scope Gets Built
We do the work covered by the claim, plus any upgrades you choose separately.
Coastal Policy Realities
What Makes Carolina Coast Claims Different
Six things about insuring a roof this close to the Atlantic that inland homeowners never deal with.
Separate Named-Storm Deductibles
Percentage-based wind deductibles are standard on coastal policies here.
Roof Age Underwriting
Coastal carriers increasingly ask about roof age and condition at renewal.
Actual Cash Value Clauses
Some policies depreciate an older roof rather than paying replacement cost.
Storm-Date Attribution
Carriers want damage tied to a specific dated event, not general wear.
Deductible Waiving Is Illegal
In South Carolina, a contractor absorbing your deductible breaks the law.
Mitigation Is Your Duty
Most policies require you to prevent further damage once you know about it.
Claims FAQs
Insurance Questions After a Coastal Storm
Many coastal South Carolina policies carry a separate deductible for named storms or wind, calculated as a percentage of your dwelling coverage rather than a flat dollar amount. On a $400,000 home a 2% wind deductible is $8,000 — very different from the $1,000 people expect.
Documented Free
Get the Roof Documented Before You Decide
No contract, no signature, no obligation to file. Just photographs and an honest read on the damage.
After the Storm
Have Your Storm Damage Documented
Tell us roughly when the storm hit and we'll tie the photographs to that date.
Hours of Operation
- Monday 9:00 AM – 8:00 PM
- Tuesday 9:00 AM – 8:00 PM
- Wednesday 9:00 AM – 8:00 PM
- Thursday 9:00 AM – 8:00 PM
- Friday 9:00 AM – 8:00 PM
- Saturday 9:00 AM – 8:00 PM
- Sunday 9:00 AM – 8:00 PM
Request a Free Quote
Tell us what's going on — we'll reply fast during business hours.